Insurance Denied Liability? What to Do After an Accident
Insurance denied liability for your accident? Learn the steps to challenge it and protect your claim. Call (833)-864-8408 for a free case review.
By Noemi Fletcher
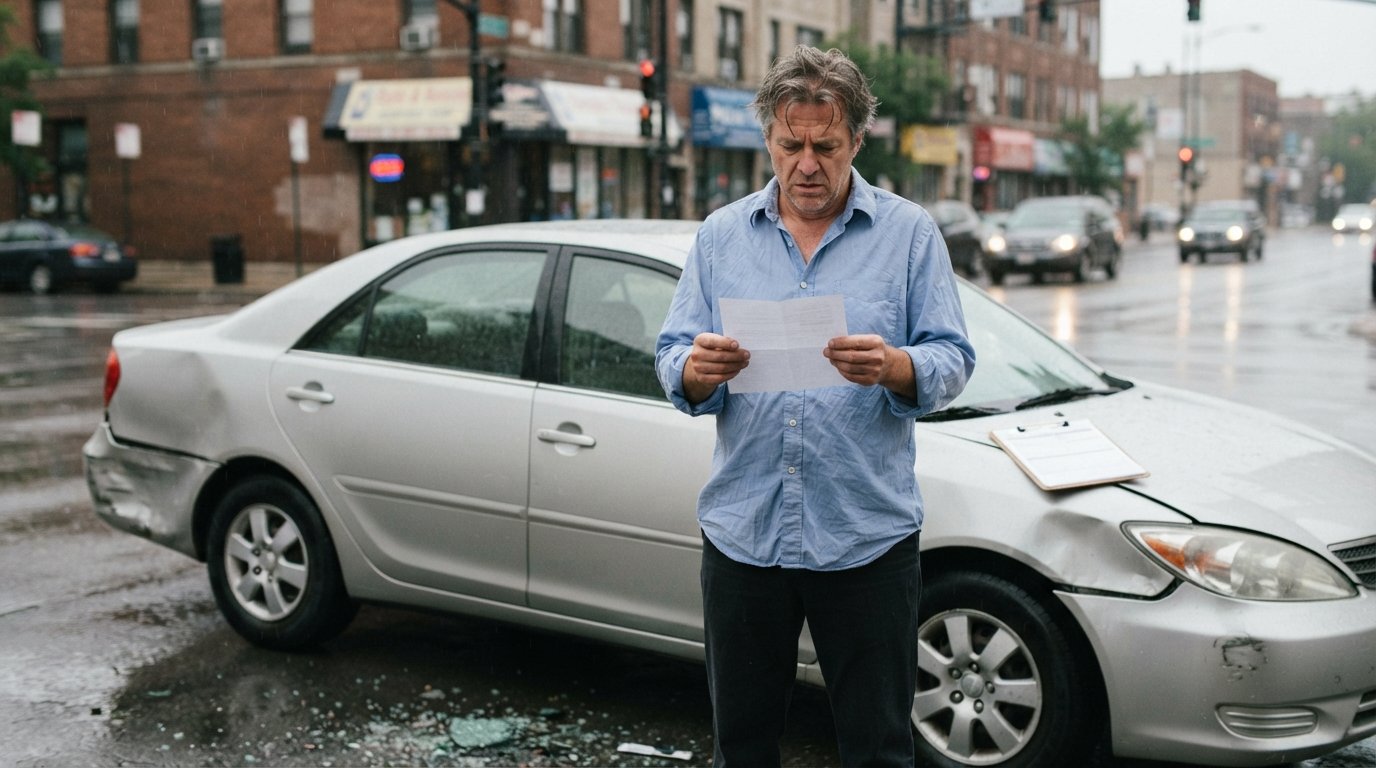
You followed every rule after the crash. You exchanged information, called the police, and filed a claim. Then the letter arrives: the other driver's insurer denies liability for your accident. Suddenly the medical bills, lost wages, and repair estimates are your problem alone, and the clock keeps ticking. Before you accept that answer as final, understand this: an early liability denial is often a negotiating position, not a verdict. Insurers deny fault for strategic reasons, and a denial can be reversed with the right evidence and pressure. This guide walks you through exactly what to do if insurance denies liability for your accident, from decoding the denial letter to forcing a stalled carrier to take your claim seriously.
Why Insurers Deny Liability Before Litigation
Insurance companies are businesses, and every claim is a cost to be minimized. When an adjuster denies liability, the decision usually reflects a calculation about risk, not a careful search for the truth. The adjuster may have found a gap in the police report, a witness who contradicts your version, or simply a file that is expensive enough to fight. Understanding this mindset matters because it tells you where to aim your rebuttal.
Internally, liability review focuses on a few core questions. Who had the right of way? Was there a traffic control device? Did either driver violate a statute? Are there inconsistencies between your statement, the police report, and the physical damage? Insurers also look for comparative fault, meaning any share of blame they can assign to you that would reduce or eliminate their payout. In many states, even a small percentage of fault can cut your recovery, and in a handful of states it can bar it entirely. The adjuster's review is not a neutral investigation; it is a defense-oriented screening designed to find reasons to pay less.
There is also a timing element. Denials often come early, before you have hired an attorney or completed treatment, because carriers know that unrepresented claimants frequently give up. A fast denial is a test of your resolve. Treat it as the opening move in a negotiation, not the final word.
Read the Denial Letter Carefully and Note Deadlines
Before you respond, slow down and study the letter. The denial letter is a roadmap of the insurer's reasoning, and it often contains the exact arguments you will need to dismantle. Look for the specific basis of the denial: was it a dispute about who caused the crash, an allegation that you were partially at fault, a claim that coverage does not apply, or a missed deadline? Each of these requires a different response.
Pay close attention to deadlines. Appeal windows, statute of limitations periods, and notice requirements can be short, and missing one can end your claim regardless of who was truly at fault. If the letter cites a policy exclusion, request the policy language in writing. If it cites a factual dispute, note every factual assertion you can challenge. Write down the date you received the letter and create a calendar of every deadline mentioned, then add your state's personal injury statute of limitations as a backstop. When in doubt, assume the deadline is sooner than you think.
Gather Independent Evidence Immediately
After a denial, evidence becomes perishable. Surveillance video is overwritten, skid marks fade, and witnesses move or forget details. The single most valuable thing you can do is preserve proof that does not depend on the insurer's goodwill. Start with the scene itself: return to the location if it is safe and photograph road layout, signage, traffic signals, and sight lines. Note weather and lighting conditions at the same time of day.
Then work through the following sources, which are the ones that most often turn a denial around:
- Traffic and security camera footage from nearby businesses, municipal traffic cameras, or doorbell cameras, requested in writing before it is overwritten.
- Witness statements collected early, with full names and contact information, especially from passengers, pedestrians, and independent drivers.
- Vehicle damage documentation, including photos from multiple angles and a repair estimate that shows impact points consistent with your version of events.
- Medical records that document the mechanism of injury and the timing of symptoms, which help connect your injuries to the crash.
- Police report supplements, 911 call recordings, and any body or dash camera footage from responding officers.
Once collected, organize everything into a single timeline. Insurers respond to coherent, documented narratives far better than to emotional appeals. A clear chronology that matches the physical evidence is hard to dismiss, and it gives your eventual demand letter or attorney a strong foundation. If your accident happened on private property, such as a parking lot or a store entrance, the evidence rules and liability standards can differ, so review guidance on accidents on private property in Pennsylvania to understand how premises liability may affect your claim.
Demand Letters and Internal Appeals Versus Filing Suit
Once your evidence is organized, you have two main paths: escalate within the insurance process or move toward litigation. The first path is a formal demand letter or internal appeal. A well-constructed demand letter restates the facts, attaches the evidence, applies the relevant traffic or liability law, and demands a specific response within a set time. It signals that you are organized and willing to fight, which often prompts a reconsideration or a more reasonable settlement offer.
If the appeal fails, the next step is filing a lawsuit. Filing suit changes the calculus because it shifts the dispute into a formal legal process with discovery, depositions, and a judge or jury. Many carriers that deny liability in the claims stage become far more reasonable once a complaint is filed, because litigation is expensive and uncertain. The decision between appealing and suing depends on the strength of your evidence, the size of your damages, and your state's deadlines. A free attorney case review can help you weigh these options without guessing.
One practical note: do not sign a release or accept a low settlement just to make the denial go away. Once you sign, the claim is over. If liability is genuinely disputed, a lawyer can often preserve your options while negotiating.
How a Free Attorney Case Review Pressures a Stalled Carrier
Insurers track which claims are represented by counsel. A claim handled by an attorney is treated differently: it is less likely to be denied on thin grounds, more likely to receive a prompt and serious evaluation, and far more likely to result in a fair offer. This is not because attorneys have special powers, but because the carrier knows that a lawyer will document the file, meet deadlines, and file suit if necessary.
A free case review through a referral service such as LawyerCaseReview connects you with experienced personal injury attorneys who evaluate your claim at no upfront cost. The review itself is confidential and carries no obligation to hire. If an attorney takes your case, they can send a demand letter on firm letterhead, request the insurer's claim file, and, when needed, file a lawsuit to keep the claim alive. For claimants facing a denial, this outside pressure is often the difference between a stalled file and a resolution.
You can also learn more about protecting your rights in disputes involving legal professionals and consumer claims by visiting AttorneyLawsuit, a legal information resource on attorney-related lawsuits and client rights. And if you are unsure whether your denial is worth fighting, a case review is a low-risk way to find out. LawyerCaseReview is not a law firm and does not provide legal advice; it connects you with participating attorneys who can evaluate your situation.
Common Mistakes That Weaken a Denied Claim
The way you respond to a denial matters as much as the denial itself. Some of the most common missteps are avoidable. Giving a recorded statement to the other insurer after a denial, for example, can create inconsistencies that are used against you. Posting about the accident on social media can undermine your credibility. Delaying medical treatment or gaps in care can be framed as evidence that your injuries were minor. And accepting a quick low offer before you understand the full extent of your damages can permanently undercut your claim.
Another frequent error is failing to document the insurer's delays. Keep a log of every call, letter, and email, including dates and the names of people you spoke with. If the carrier is acting in bad faith, that record becomes valuable. Most importantly, do not assume the denial is the end of the road. Insurers deny liability every day, and those denials are reversed every day when claimants respond with evidence and persistence. The next step is yours, and it is worth taking seriously.
An accident denial can feel like a closed door, but it is usually a negotiation tactic. Read the letter, preserve the evidence, escalate through a demand or appeal, and bring in professional pressure when the carrier stalls. With a clear record and the right support, a disputed liability claim can often be turned into a fair recovery.