Pain and Suffering Damages: How They Are Proven and Valued
Prove pain and suffering damages with the right evidence. For a free case review, call (833)-864-8408 and connect with a personal injury attorney.
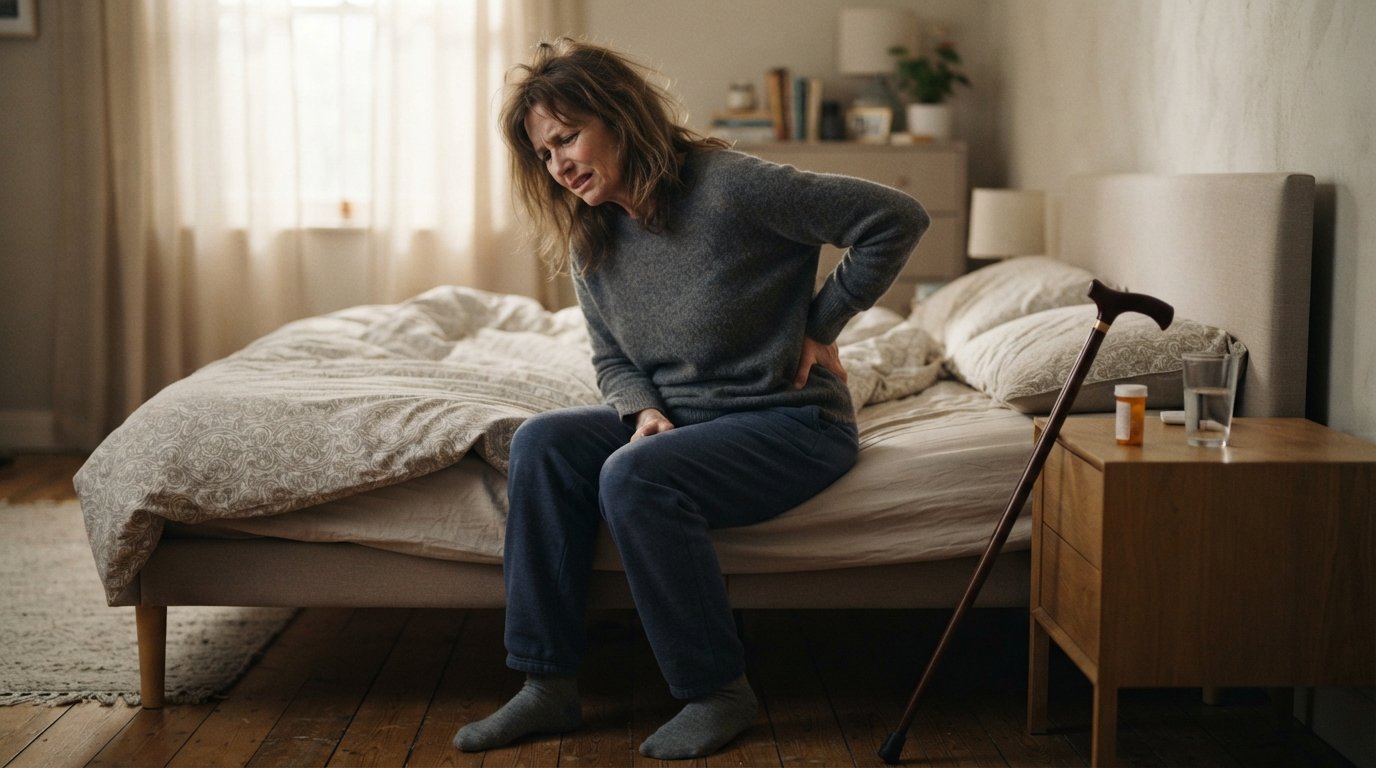
After a serious injury, the bills and lost wages are easy to see, but the hardest part to put a number on is often the one that matters most: the pain, the loss of enjoyment, the sleepless nights, and the constant worry. Insurance adjusters know this, and they routinely undervalue these non-economic losses or dismiss them as subjective. Understanding how pain and suffering damages are proven and valued gives you a realistic picture of what your claim is worth and how to push back when an offer falls short. This guide breaks down the evidence that matters, the calculation methods insurers use, and the factors that can make or break your claim.
What Pain and Suffering Means in a Personal Injury Claim
Pain and suffering damages are a category of non-economic compensation intended to account for the physical and emotional toll of an injury. They are separate from medical expenses, which reimburse you for treatment, and from lost wages, which replace income you could not earn. Non-economic damages also include loss of enjoyment of life, such as giving up hobbies, difficulty sleeping, anxiety, and the strain on relationships. Emotional distress is a related but distinct component: it focuses on psychological harm like fear, humiliation, or post-traumatic stress, while pain and suffering broadly covers the physical discomfort and diminished quality of life. In practice, juries and insurers often treat these concepts together because the evidence overlaps.
Most states do not have a fixed formula for non-economic damages, but many have caps, especially in medical malpractice cases. That is why documentation and a clear narrative are so important: the same injury can produce wildly different awards depending on how well the impact is proven. If you want a general overview of the math, our guide on how pain and suffering damages are calculated walks through the basics, while this article focuses on evidence and valuation from the insurer's perspective.
How Pain and Suffering Is Proven: Building the Evidence Record
Insurers do not take subjective complaints at face value. They look for corroboration from medical records, third-party observations, and your own daily life. The strongest claims tell a consistent story from the moment of injury through treatment and recovery. Gaps in treatment, inconsistent statements, and pre-existing conditions give adjusters room to argue that your pain is exaggerated or unrelated to the accident. The following types of evidence do the heavy lifting.
- Treating-provider records and narratives: Notes from your physicians, specialists, and physical therapists that describe pain levels, limitations, and progress. A letter from your doctor explaining why your pain is consistent with the injury carries more weight than a one-line diagnosis.
- Daily-life impact journals: A contemporaneous log of pain ratings, sleep disruptions, missed activities, and emotional struggles. Judges and juries find these credible when they are detailed and consistent, not written all at once before trial.
- Testimony from family and friends: Lay witnesses who describe changes in your mood, mobility, and participation in family life. Their observations are harder for insurers to dismiss than your own statements.
- Vocational and recreational evidence: Records showing you can no longer perform certain job tasks or enjoy hobbies, plus photographs or videos that illustrate limitations.
Medical imaging, objective tests, and expert testimony from an economist or life-care planner can also help quantify the future impact of chronic pain. The key is to connect each piece of evidence to a specific limitation: not just that your back hurts, but that you cannot sit through a workday or lift your child. When you request a free case review through a service like CheapInjuryLawyer, an experienced attorney can help you organize these records and identify the gaps before an insurer uses them against you.
Valuation Methods Insurers and Juries Use
Once the evidence is in place, the value of pain and suffering is typically estimated using one of two methods. The multiplier method takes your economic damages (medical bills and lost wages) and multiplies them by a factor, usually between 1.5 and 5, depending on the severity of the injury. A minor soft-tissue injury might land near the low end, while a spinal cord injury or traumatic brain injury could justify a multiplier of 4 or 5. The per-diem method assigns a daily dollar figure to your pain and suffering and multiplies it by the number of days you are expected to suffer. For example, a $100 per-day figure over two years equals roughly $73,000. Insurers often prefer the multiplier method because it keeps payouts tied to hard costs, while plaintiffs' attorneys may use per-diem calculations to highlight long recovery periods.
Neither method is a legal rule. They are negotiation and trial aids, and courts do not require a jury to use either one. In practice, the final number depends on the jurisdiction, the clarity of the evidence, the credibility of the plaintiff, and the skill of the attorneys. A jury that hears a compelling story about a formerly active person who can no longer hike or play with their grandchildren may award far more than a formula suggests. That is why the evidence record described above matters as much as the math.
Factors That Increase or Reduce the Value of a Claim
Several factors can move a pain and suffering claim up or down. Pre-existing conditions are a common battleground: if you had arthritis or a prior back injury, the insurer will argue that your current pain is not new. The counter is to show that the accident aggravated the condition or made it symptomatic when it was previously manageable. Gaps in treatment are another red flag; a long break in care suggests you were not suffering as much as claimed, even if the real reason was cost or insurance issues. Documenting those reasons can neutralize the argument.
Other factors include the severity and permanence of the injury, your age and activity level before the accident, the clarity of liability, and whether the case goes to trial. Cases with disputed fault or low insurance policy limits often settle for less. Conversely, a clear rear-end collision with substantial medical evidence and a sympathetic plaintiff tends to produce stronger offers. If you are unsure how these factors apply to your situation, a free case review can provide a realistic range based on similar claims in your state.
Why a Free Case Review Helps You Gauge Realistic Ranges
Insurers have years of data on similar injuries, and they use it to make initial offers that are often far below fair value. An experienced personal injury attorney can compare your evidence to verdicts and settlements in your jurisdiction, identify weaknesses before they are exploited, and negotiate from a position of knowledge. Many attorneys work on contingency, meaning you pay nothing upfront and only a percentage of the recovery if you win. A free case review is a low-risk way to get a professional assessment of your pain and suffering claim, understand the likely range, and decide whether to pursue it further. LawyerCaseReview.com is not a law firm and does not provide legal advice, but it connects injury victims with participating attorneys who can evaluate the strength of the evidence and explain the next steps.
Pain and suffering damages are rarely simple to prove, but they are not mysterious. The right medical records, a consistent daily journal, testimony from people who know you, and a clear explanation of how your life has changed can turn a subjective complaint into a persuasive claim. Whether you handle the negotiation yourself or work with counsel, understanding how these damages are proven and valued helps you avoid accepting a low offer and gives you a realistic path toward fair compensation.