Sole Proprietor Bankruptcy: Chapter 7 vs 13 Options
Compare bankruptcy options for sole proprietors chapter 7 versus 13 and protect your business assets. Call (833)-864-8408 for a free case review.
By Noemi Fletcher
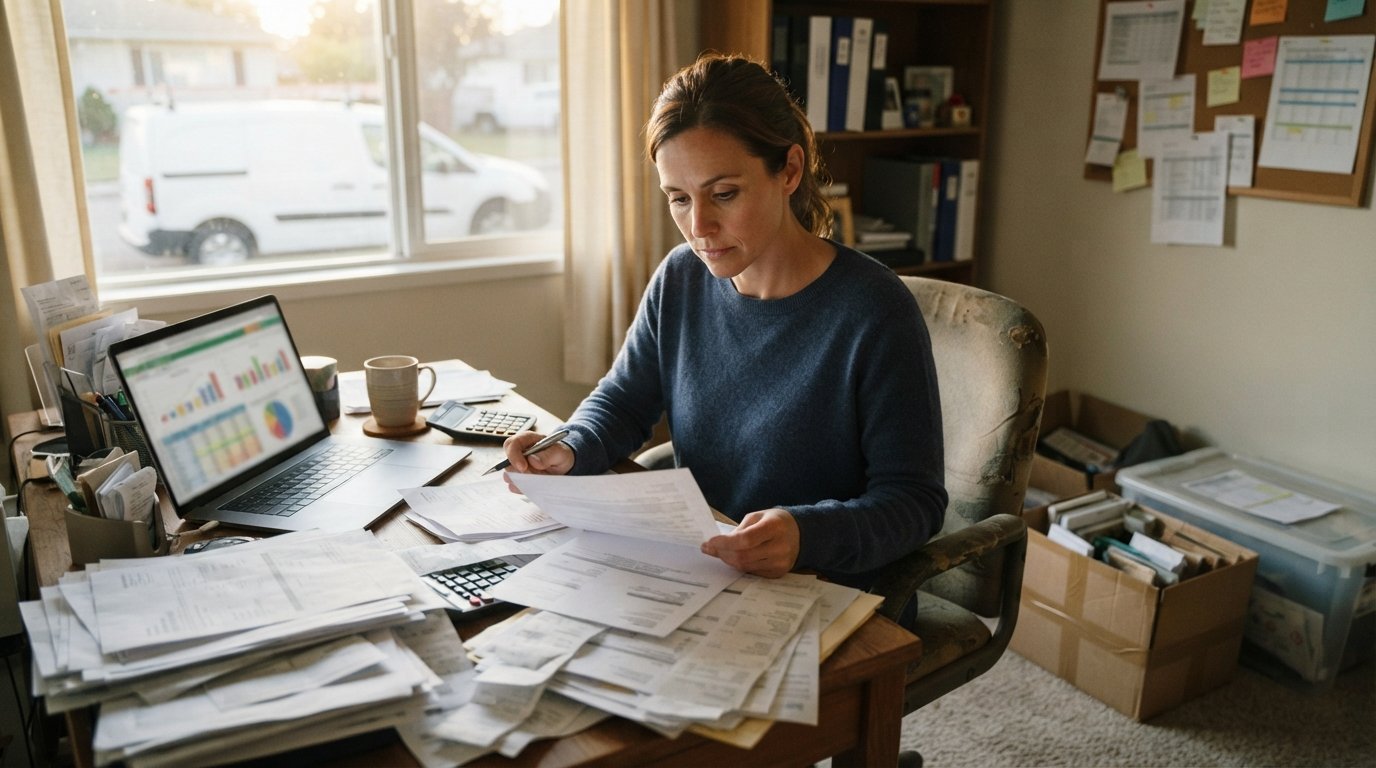
Facing financial distress as a sole proprietor feels uniquely personal because your business and your household finances are legally intertwined. Unlike a corporation or LLC, a sole proprietorship does not create a separate legal entity, so business debts are your personal debts. When revenue slows and creditors begin calling, the decision between Chapter 7 and Chapter 13 bankruptcy becomes a strategic choice about which assets you keep, which debts disappear, and whether you can continue operating your business during repayment. This guide breaks down the bankruptcy options for sole proprietors chapter 7 versus 13, with practical steps for preparing a case review and protecting the tools, inventory, and vehicle you rely on to earn a living.
How Sole Proprietorship Debts Interact with Personal Bankruptcy
Because a sole proprietorship has no separate legal identity, filing a personal bankruptcy simultaneously addresses your business liabilities and your consumer debts. Business credit cards, vendor accounts, lease obligations, and business loans are treated as your personal obligations. If you file Chapter 7, those debts are discharged alongside your medical bills and personal loans, provided they are not excepted from discharge. If you file Chapter 13, they are included in your repayment plan and whatever remains unpaid at the end of the plan is typically discharged.
This unity of business and personal liability cuts both ways. On one hand, it simplifies the process: you do not need a separate business bankruptcy filing. On the other hand, it means your personal assets are exposed to business creditors, and your business assets are part of the bankruptcy estate. Understanding this interplay is the foundation for choosing between Chapter 7 and Chapter 13. For a deeper look at how overwhelming healthcare costs can compound these decisions, our guide on medical debt bankruptcy options explains how medical bills interact with business debt in a personal filing.
One common misconception is that closing the business is required in Chapter 7. In reality, a sole proprietor can continue operating as a sole proprietor after filing, but the bankruptcy trustee may liquidate non-exempt business assets. Chapter 13, by contrast, is designed to let you keep operating while you repay creditors from future income. The choice hinges on your income, your assets, and whether your business can generate enough cash flow to fund a plan.
Chapter 7 for Sole Proprietors: Liquidation and Discharge
Chapter 7 is a liquidation bankruptcy. A trustee is appointed to review your assets, sell any non-exempt property, and distribute the proceeds to creditors. For sole proprietors, the critical question is which business assets are exempt. Exemptions vary by state, but many states offer wildcard exemptions and specific protections for tools of the trade, inventory, and a vehicle. If your business assets fit within these exemptions, you may be able to keep them and continue operating after discharge.
The means test is the gatekeeper for Chapter 7. It compares your current monthly income to the median income for your state and household size. For self-employed filers, income is calculated using a six-month average of gross receipts minus ordinary and necessary business expenses. This is where careful recordkeeping matters. If your profit and loss statements are incomplete or inconsistent, the means test calculation may be challenged, and you could be pushed into Chapter 13. The means test allows deductions for business expenses, but the definitions are strict and require documentation.
Exemptions are the second major consideration. A sole proprietor who needs a vehicle for deliveries, tools for construction, or inventory for retail sales should review state exemption statutes carefully. Some states offer a wildcard exemption that can be applied to any property, while others have specific caps for tools of the trade. In some cases, a sole proprietor can use federal exemptions instead of state exemptions, which may provide more generous protection for certain assets. The key is to plan before filing: converting non-exempt assets into exempt assets shortly before bankruptcy can be viewed as fraudulent and is not advisable.
Chapter 7 offers a fresh start relatively quickly, often with a discharge in three to four months. However, it may require you to surrender non-exempt business assets, and it can affect your ability to obtain business credit in the future. It is best suited for sole proprietors with limited income, few non-exempt assets, and business debts that are unlikely to be repaid through a plan.
Chapter 13 for Sole Proprietors: Reorganization and Continued Operation
Chapter 13 is a reorganization bankruptcy for individuals with regular income. A sole proprietor with a stable business can propose a plan to repay creditors over three to five years, often paying a percentage of unsecured debts based on disposable income. The plan must be feasible, in good faith, and comply with the best interests of creditors test, which ensures creditors receive at least as much as they would in Chapter 7.
For many sole proprietors, Chapter 13 is attractive because it allows them to keep operating the business and protect non-exempt assets by paying their value through the plan. Instead of surrendering equipment or inventory, you can propose to pay creditors an amount equal to the non-exempt equity. This can be particularly valuable if your business relies on specialized tools, a fleet vehicle, or inventory that would be difficult to replace. Chapter 13 also provides a automatic stay that stops collection actions, foreclosures, and repossessions, giving you breathing room to reorganize.
Self-employed income in Chapter 13 is evaluated based on your projected disposable income. The trustee and court will scrutinize your profit and loss statements, tax returns, and business projections. A well-prepared plan should account for fluctuations in revenue, seasonal slowdowns, and necessary business expenses. If your income exceeds the median for your state, you may be required to commit all projected disposable income to the plan for five years. If it is below median, the plan period may be three years, though you can propose a longer plan if necessary.
Chapter 13 also allows you to cure mortgage arrears, pay off tax debts, and deal with secured creditors over time. For a sole proprietor who has fallen behind on a business vehicle loan or equipment lease, Chapter 13 can provide a structured path to catch up. The tradeoff is a longer commitment and the risk that the plan may fail if your income drops. However, a failed Chapter 13 can often be converted to Chapter 7 or dismissed, so it is not necessarily a dead end.
Comparing Chapter 7 and Chapter 13 for Sole Proprietors
The right choice depends on your income, assets, business viability, and goals. The following list summarizes the key differences to help you evaluate your options.
- Asset protection: Chapter 7 relies on exemptions to protect business assets; Chapter 13 allows you to keep non-exempt assets by paying their value through the plan.
- Income qualification: Chapter 7 requires passing the means test; Chapter 13 requires sufficient disposable income to fund a plan.
- Business continuation: Both chapters allow you to continue operating, but Chapter 7 may involve liquidation of non-exempt business property, while Chapter 13 is designed to preserve the business.
- Duration: Chapter 7 is typically completed in a few months; Chapter 13 involves a three to five year repayment plan.
- Credit impact: Both remain on your credit report for years, but Chapter 13 may be viewed more favorably by some lenders because it demonstrates a commitment to repay.
It is also important to consider the discharge of business debts. In Chapter 7, most business debts are discharged, but debts incurred through fraud or misrepresentation may be excepted. In Chapter 13, the same exceptions apply, but the plan may pay a portion of these debts. Taxes are another factor: recent income taxes are generally not dischargeable in Chapter 7, but Chapter 13 can provide a payment plan for them. If tax debt is a major issue, Chapter 13 may be the better option.
For sole proprietors with significant personal assets that are not exempt, Chapter 13 can be a lifeline. For those with limited assets and income below the median, Chapter 7 offers a faster path to relief. A free case review with an experienced bankruptcy attorney can help you model both scenarios and choose the one that fits your situation.
Preparing for a Free Case Review: Documents and Steps
Whether you are leaning toward Chapter 7 or Chapter 13, preparation is critical. A bankruptcy attorney will need a clear picture of your financial situation, including business and personal finances. Gathering the right documents in advance can streamline the process and improve your chances of a favorable outcome. The following steps outline what to prepare for a free case review.
- Compile profit and loss statements: Provide at least six months of profit and loss statements, ideally twelve, to show income trends and business expenses. These will be used for the means test and plan feasibility.
- Gather tax returns: Include personal and business tax returns for the past two to three years, along with any recent notices from the IRS or state taxing authority.
- List all debts: Create a comprehensive list of business and personal debts, including creditor names, amounts owed, and collateral. Include leases, loans, credit cards, and tax obligations.
- Inventory your assets: Document business equipment, inventory, vehicles, bank accounts, and accounts receivable. Note which items you need to continue operating.
- Review contracts and leases: Bring copies of business leases, equipment leases, and any pending lawsuits or judgments. These may affect your options.
During the case review, be honest and thorough. Hiding assets or income can lead to dismissal of your case or even criminal charges. An attorney can help you understand which exemptions apply and how to structure your filing. If you are unsure where to start, resources like AttorneyLawsuit provide general information on legal disputes and client rights, which can be helpful as you navigate the process. However, for specific advice about your bankruptcy, consult a licensed bankruptcy attorney in your state.
Keep in mind that LawyerCaseReview.com is not a law firm and does not provide legal advice. The information here is for educational purposes only. A free case review with a participating attorney can help you evaluate your bankruptcy options for sole proprietors chapter 7 versus 13 and make an informed decision.
Exemptions, the Means Test, and Self-Employment Income
Two technical hurdles often determine the chapter choice for sole proprietors: exemptions and the means test. Exemptions protect certain assets from liquidation in Chapter 7 and set the baseline for what you must pay in Chapter 13. Common exemptions include a homestead exemption, a vehicle exemption, a tools of the trade exemption, and a wildcard exemption. Some states allow you to choose between state and federal exemptions, and the choice can significantly affect your case. For example, if you have substantial equity in a vehicle used for business, the federal vehicle exemption may be more generous than your state's.
The means test for self-employed filers requires careful calculation of your current monthly income. You must average your gross income over the six months before filing and subtract ordinary and necessary business expenses. The remaining amount is compared to the median income for your household size. If it is below the median, you generally qualify for Chapter 7. If it is above, you may still qualify after deducting allowed expenses, but the analysis is more complex. Business expenses must be documented and reasonable; inflating expenses to pass the means test is not acceptable.
Chapter 13 disposable income is calculated similarly but looks forward rather than backward. You must project your income and expenses over the plan period. For sole proprietors with irregular income, this can be challenging. A common approach is to use a conservative projection based on historical averages and to build in a cushion for slow months. The court will review your plan for feasibility, so it is better to propose a realistic plan than an overly optimistic one that fails later.
If you have significant business assets that are not exempt, Chapter 13 may be the only way to keep them. If your business is not viable and you are ready to close it, Chapter 7 may provide a faster fresh start. In either case, a thorough review of your profit and loss records is essential. Lenders and trustees will want to see that your business income is stable enough to support a plan or that your expenses are legitimate.
Next Steps: Getting Help with Your Decision
Choosing between Chapter 7 and Chapter 13 as a sole proprietor is not a decision to make alone. The stakes are high, and the rules are complex. A free case review with an experienced bankruptcy attorney can help you understand how the means test applies to your self-employment income, which exemptions protect your tools and inventory, and whether Chapter 13 can help you keep your business running. LawyerCaseReview.com connects you with top-rated attorneys who can evaluate your situation confidentially and without obligation.
Before your review, gather your profit and loss statements, tax returns, debt list, and asset inventory. Be prepared to discuss your business goals: do you want to continue operating, or are you ready to close and move on? Your answer will shape the advice you receive. If you have questions about legal malpractice or attorney misconduct, AttorneyLawsuit offers resources, but for bankruptcy guidance, rely on a licensed attorney in your state.
Bankruptcy is a tool for recovery, not a failure. With the right preparation and the right chapter, you can resolve business debts, protect essential assets, and rebuild your financial future. Take the first step by scheduling a free case review and exploring your bankruptcy options for sole proprietors chapter 7 versus 13 today.